What is the difference between cash and accrual accounting?
Cash accounting generally follows receipt of income and payment of expenses. Accrual accounting generally follows when income is earned and expenses are incurred under the applicable rules. Tax exceptions, eligibility and method-change rules can affect the result.
Put The Basis On The Report
Before comparing two profit and loss statements, check their reporting dates and basis. An unpaid customer invoice may appear differently in cash and accrual reports. That does not mean one report is broken. It means they may be answering different timing questions.
A Simple Invoice Example
Suppose a business issues a $12,000 customer invoice in December and receives payment in January. In a simplified accrual example, the revenue is recorded when earned; in a simplified cash example, receipt controls. Actual tax treatment can involve additional rules, so this illustration is not permission to move income between years.
Do Not Change The Tax Method With A Button
Many programs can display more than one reporting basis. That display option does not establish eligibility for a tax accounting method or authorize changing it. Identify the method used on the filed return and review the tax requirements before changing how an item is treated.
Choose Information That Helps You Operate
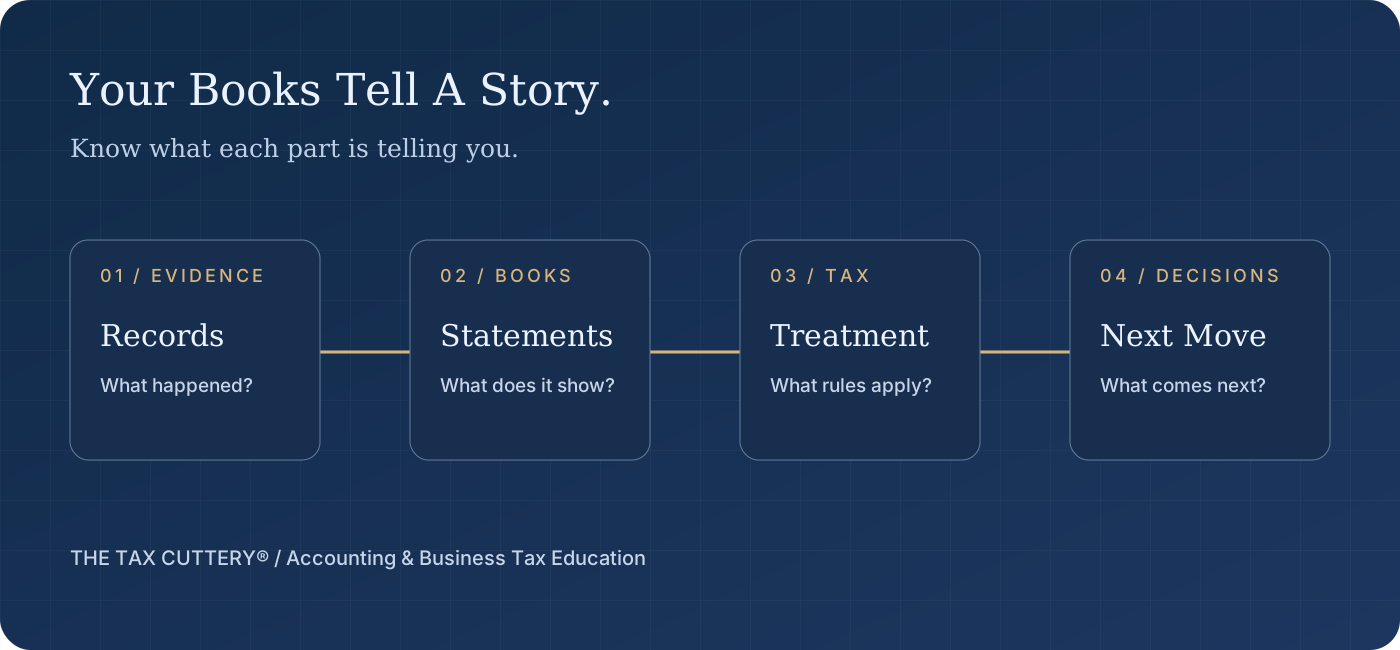
A management report can help explain receivables and commitments while the tax file follows the permitted method. Document the bridge between them. Good accounting makes those differences visible so that planning starts with a clear explanation rather than an apparent contradiction.
Bring These Questions Into The File.
- Reporting period and stated accounting basis
- Method used on prior filed returns
- Receivables, payables and relevant inventory facts
- Proposed changes and the reason for them
Read The Primary Sources.
IRS references for the federal tax and recordkeeping distinctions. Examples on this page are educational, not a determination of your tax treatment.
IRS: Accounting Periods And Methods ↗IRS: Starting A Business And Keeping Records ↗